
“We Buy Houses for Cash.”
You’ve probably seen the postcards, text messages, online ads, and signs.
Some come from investors who intend to purchase properties directly.
Others may come from wholesalers who put properties under contract and then attempt to assign those contracts to other buyers.
Those are different transaction structures, and sellers should understand which one they are dealing with before signing.
“Cash buyer” does not always tell you who will ultimately purchase the property
The contract, buyer identity, funding, assignment rights, diligence period, and cancellation provisions can tell you much more than the advertisement.
What Is a Direct Cash Buyer?
A direct cash buyer generally intends to purchase the property using available funds rather than obtaining a conventional mortgage for the transaction.
That buyer could be an individual investor, investment company, institutional buyer, landlord, renovation company, or another entity.
Cash does not mean there will be no diligence, inspections, title work, or contractual conditions.
It primarily means the purchase is not dependent on conventional mortgage financing.
What Is a Real Estate Wholesaler?
A real estate wholesaler may enter into a purchase agreement and then seek another investor who will ultimately acquire the property or contractual rights, depending on the structure and applicable law.
One common structure involves assigning the purchase contract to another buyer for a fee.
Wholesaling rules, licensing requirements, marketing restrictions, and disclosure requirements vary by jurisdiction, so sellers and agents should avoid assuming every transaction works the same way.
The important question is not whether someone calls themselves a “cash buyer.” It is what the contract actually allows them to do.
Ask Who Is Actually Buying the Property
Sellers should know the legal name of the person or entity signing the purchase agreement.
If a company name appears on the contract, ask what that company does and who will ultimately provide the funds at closing.
Useful questions include:
- Are you purchasing the property yourself?
- What legal entity will appear on the closing documents?
- Can this purchase agreement be assigned?
- Do you currently have funds available for the purchase?
- What due-diligence rights do you have?
- Under what circumstances can you cancel?
- What happens if another investor is not found?
Read the Assignment Language
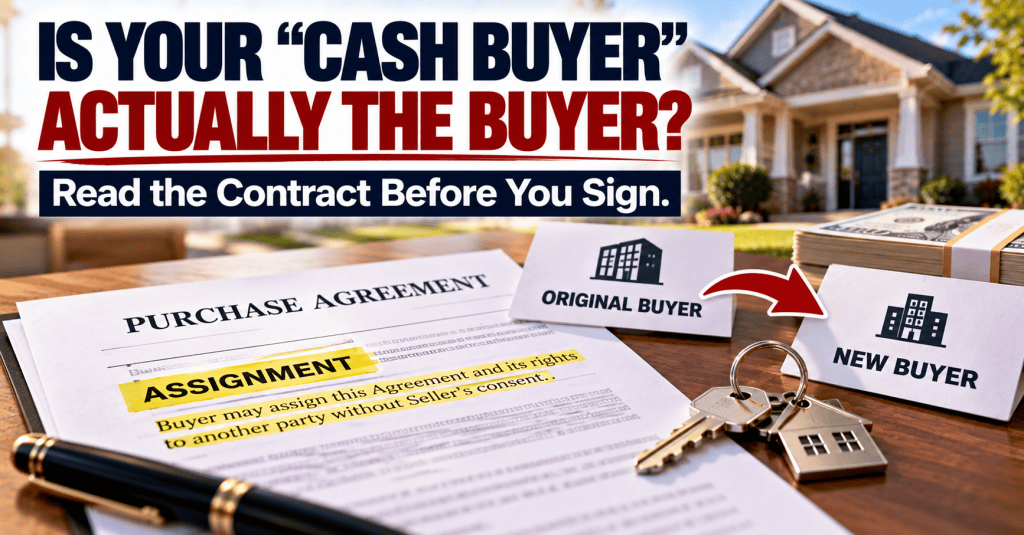
One of the most important parts of the purchase agreement may be whether the buyer can assign its rights under the contract.
Assignment language can allow another party to step into the original buyer’s contractual position, subject to the agreement and applicable law.
That is not automatically negative.
But the seller should know that possibility exists before signing.
Look at the contract
If you care who actually buys the home, understand whether the agreement lets the original buyer transfer the contract to someone else.
Ask for Evidence of Funding
If a buyer represents that they intend to purchase using cash, sellers and their agents may want appropriate evidence showing the buyer’s ability to perform.
The exact documentation depends on the transaction.
A proof-of-funds document can be one piece of that evaluation, although sellers should still consider the complete contract and buyer.
Pay Attention to the Due-Diligence Period
A buyer may have time after signing to inspect the property, review information, evaluate the numbers, or terminate under certain contractual provisions.
A long or highly flexible diligence period may create more uncertainty for the seller.
That does not necessarily make the contract bad.
It means the seller should understand how long the buyer has to make a final decision.
Understand the Earnest Money
The amount, timing, and treatment of earnest money may provide useful context when evaluating an offer.
Sellers should understand:
- How much earnest money is being deposited
- When it must be deposited
- Who holds it
- When it becomes non-refundable, if applicable
- What the contract says happens after termination
A High Offer Is Not Helpful If It Cannot Close
Sellers naturally focus on purchase price.
But an offer also needs to be evaluated based on the buyer’s ability and obligation to perform.
The strongest offer is not simply the one with the highest number. It is the combination of price, terms, funding, diligence, and likelihood of closing.
Compare the Contract, Not the Advertisement
Marketing phrases like “cash buyer,” “any condition,” “fast closing,” or “no repairs” are not substitutes for contract terms.
Sellers should review what is actually written in the agreement.
| What to Check | Why It Matters |
|---|---|
| Buyer Identity | Shows who is legally agreeing to purchase the property. |
| Assignment Rights | Shows whether another party may eventually take over the contract. |
| Funding | Helps evaluate how the purchase is expected to be completed. |
| Due Diligence | Determines what the buyer can investigate and when they may have termination rights. |
| Closing Terms | Defines the expected timing, costs, title requirements, and other closing obligations. |
Wholesalers and Direct Buyers Can Both Be Legitimate
It is important not to treat the transaction structure itself as proof that something is wrong.
Real estate investors use different acquisition strategies.
The issue is transparency.
Sellers should understand what they are signing and what the buyer intends to do under that agreement.
Where a Real Estate Agent Can Help
This is one reason sellers may benefit from having a knowledgeable real estate professional involved even when they are considering an off-market offer.
The agent can help compare the proposed transaction with other available selling paths.
That comparison may include:
- Likely open-market value
- Existing cash offers
- Buyer terms
- Repair requirements
- Closing expenses
- Potential carrying costs
- Expected net proceeds
Where EasyHomeSaleAgent.com Fits
The playbook’s solution is to help agents bring institutional-buyer options directly into the seller conversation rather than leaving homeowners to evaluate random cash-buyer advertisements entirely on their own.
Give the seller more than one offer to evaluate
EasyHomeSaleAgent.com can help participating agents explore multiple preliminary institutional-buyer options and compare them alongside a traditional listing strategy.
Preliminary offers, buyer interest, property eligibility, diligence, proof-of-funds documentation, final contract terms, and closing timelines vary.
Compare Multiple Buyers When Possible
One of the problems with responding to a single advertisement is that the homeowner may have only one number to consider.
That makes it difficult to know whether the offer is competitive.
Where possible, compare more than one buyer or compare the off-market offer with a realistic traditional-sale estimate.
More useful than “Is this a good offer?”
“How does this offer compare with the seller’s other realistic options?”
Watch for Last-Minute Changes
Sellers should pay attention if important terms begin changing as the closing date approaches.
A buyer may have legitimate reasons for renegotiating after discovering new property information.
But sellers should understand exactly what changed, why it changed, and what their contractual options are before agreeing.
Don’t Sign What You Don’t Understand
Purchase agreements are legal contracts.
If a seller is unsure about assignment language, cancellation rights, legal obligations, or other contract provisions, an appropriate attorney or qualified professional may need to review the agreement.
A fast closing is not worth signing a contract the homeowner does not understand.
A Simple Cash-Buyer Verification Checklist
Know who or what entity is actually signing the agreement.
Understand whether the contract can be transferred to someone else.
Ask how the purchase is expected to be financed and review appropriate documentation.
Know when the buyer can cancel or renegotiate.
Look at price, terms, risk, timeline, and expected proceeds alongside other available options.
Key Takeaways
- Not every cash-buyer business uses the same transaction model.
- Wholesaling itself is not automatically improper, but sellers should understand how the transaction is structured.
- Review buyer identity, assignment rights, funding, diligence, earnest money, and cancellation provisions.
- Marketing claims should never replace reading the actual contract.
- Multiple buyer options can provide useful context for evaluating an off-market offer.
- If the legal terms are unclear, get appropriate professional advice before signing.
Frequently Asked Questions
What is the difference between a cash buyer and a wholesaler?
A direct cash buyer generally intends to purchase the property using available funds. A wholesaler may use a contract-based strategy that involves locating another investor or assigning contractual rights, subject to the agreement and applicable law.
Is real estate wholesaling legal?
Laws, licensing requirements, disclosure obligations, advertising rules, and permissible transaction structures vary by state and jurisdiction. Sellers and investors should confirm the requirements that apply to their transaction.
How do I know if a cash buyer can actually close?
Review the buyer’s identity, the purchase agreement, funding documentation where appropriate, earnest money, due-diligence terms, closing requirements, and the buyer’s obligations under the contract.
Before Signing a Cash Offer
Know who the buyer is and what the contract actually says.
EasyHomeSaleAgent.com can help participating agents bring multiple preliminary institutional-buyer options into the seller conversation.
See How It WorksThis article is for general educational purposes and is not legal advice. Real estate wholesaling laws, licensing requirements, assignment rules, disclosures, contracts, buyer requirements, and transaction practices vary by jurisdiction.


Leave a Reply